
Most home loan applications in Brisbane do not fail because the applicant is unemployable or unlucky. They fail because the file tells a story the lender cannot underwrite. A solid income means little if your declared expenses do not match your bank statements, or if an unused credit card limit quietly reduces what you can borrow. Understanding how a home loan assessment works lets you fix problems before they reach a credit assessor’s desk. This guide covers the main tests, the documents behind them, and the mistakes we see most often from working families, first home buyers and property investors.
Table of Contents
- Quick Takeaways
- How the Serviceability Test Works
- Credit History and Repayment Record
- Income Verification for Working Families
- Deposit and Genuine Savings
- Property Valuation and Security
- Common Reasons Applications Get Declined
- Assessment Rules for Specialised Scenarios
- Preparing Your Application Before Lodgement
- Frequently Asked Questions
- References
Quick Takeaways
| Key Insight | Explanation |
|---|---|
| Serviceability decides most files | Lenders test whether you can repay at a rate at least 3 percentage points above the offered rate. Run your own budget at that higher figure before you start looking at properties. |
| Declared expenses must match your statements | Assessors compare your declared living costs with bank transaction data. Round, low estimates are easy to spot and slow the file down. |
| Unused credit limits still count | A card with a zero balance is generally assessed as if it were fully drawn. Close cards you do not use before you lodge. |
| Job changes reset the clock | Probation periods and a recent change of employer can reduce the income a lender will accept. Time any move around your settlement date. |
| Savings need a visible history | Lenders want to see where the deposit came from and how it built up over time. A single large transfer invites questions. |
| The valuation can cap your loan | If the valuer lands below the contract price, the lender lends against the lower figure and you fund the gap. Check recent comparable sales early. |
How the Serviceability Test Works
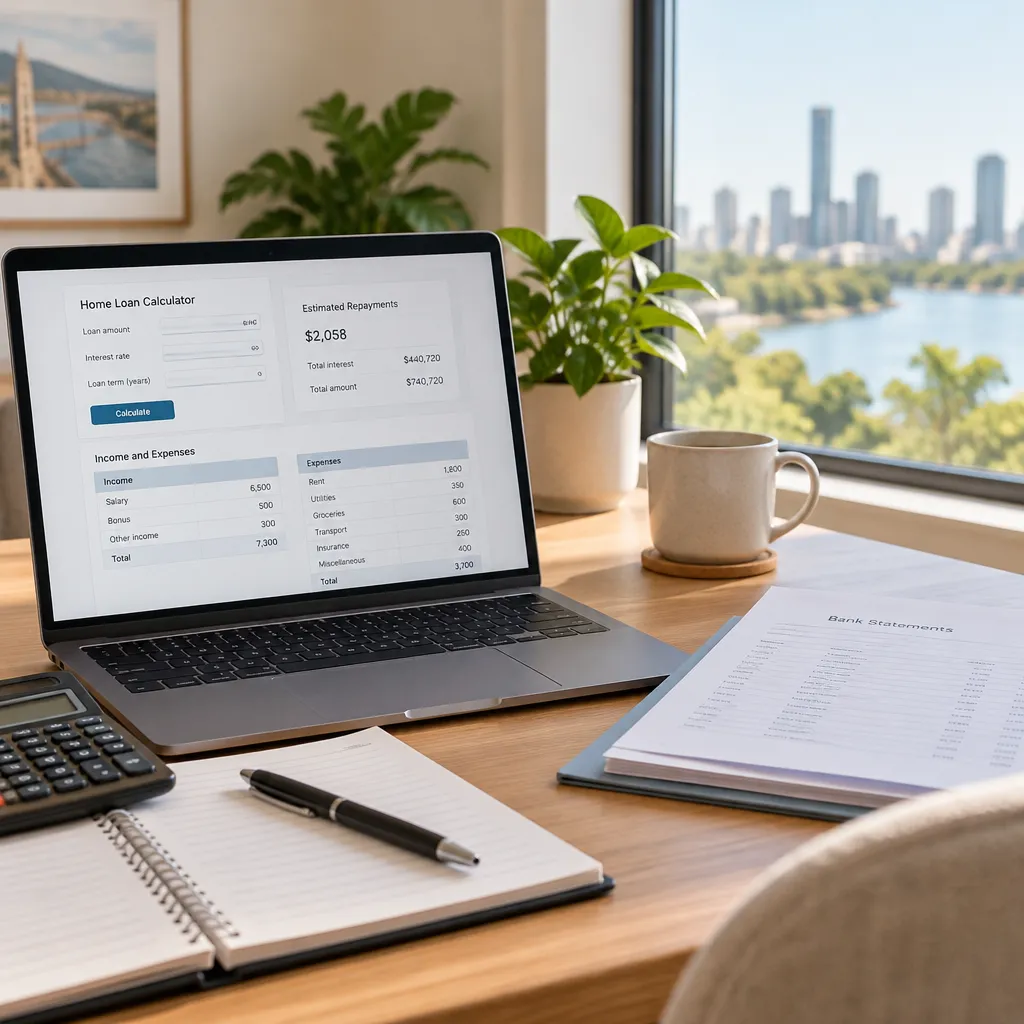
Serviceability is the question that decides most home loan assessments. The lender wants to know whether your income can cover repayments after living costs, existing debts and other commitments are taken out. Under the regulator’s guidance, lenders must test your ability to repay at a buffer of at least 3 percentage points above the offered rate. A loan offered at 6 per cent is assessed as if it were 9 per cent.
The assessment buffer in practice
The buffer catches more people than any other rule. A borrower who meets the repayment comfortably at the offered rate can still be declined once the same loan is tested at the higher assessment rate. Run your numbers at the buffer rate before you shop, not after an assessor tells you the answer.
Living expenses and the declaration problem
Lenders do not rely on your declared budget alone. Assessors apply a benchmark living expense figure, and if your declared spending is lower, they will usually use the higher of the two. Declaring $1,200 a month when your statements show $3,000 costs you credibility fast. Work from real spending over several months and include school fees, insurance, childcare, subscriptions and car running costs.
Rental income and existing debts
Rent from an investment property is usually counted at a discount rather than in full, and rent from a property you are about to vacate may not be counted at all. Credit card limits are generally assessed as if fully drawn, and a personal loan you are nearly finished with still counts as a commitment until it is repaid. Close what you no longer use before you apply.
Pro tip: Use a borrowing calculator with the buffer rate applied, not the advertised rate. If the answer feels uncomfortable, you have found the real limit on your purchase price before it costs you a property.
Credit History and Repayment Record
Your credit report is often the first document a lender reads, sometimes before they look at a single payslip. Credit reporting bodies in Australia, including Equifax, Experian and illion, hold the records. The report shows repayment history, defaults and how often you have applied for credit. Pull your own report from each bureau before you apply, because errors are common and an unexplained default can stop an application cold.
A clean credit file will not win the loan on its own, but a messy one can lose it before anyone looks at your income.
Credit enquiries and multiple applications
Every formal credit application leaves an enquiry on your file. Several applications for car finance, a phone contract and a store card in the same month look like a household under cash pressure. Limit applications to the lender you actually intend to use, and get your position assessed before you apply anywhere else.
Buy now, pay later and late payments
Buy now, pay later accounts appear on many credit files, and assessors treat them as credit commitments even when the balance is zero. A pattern of late fees, even small ones, tells a cash flow story that a serviceability calculation alone will not capture. If you have a history of missed payments, explain what happened and show the account has been stable since.
Income Verification for Working Families
Income is verified through documents, not through what you tell a broker. PAYG employees usually provide recent payslips and sometimes an employer letter or a group certificate. Lenders want stable, ongoing income, and they check whether your current role continues work you have been doing for a while. In a two income household, both incomes are assessed, and each one needs its own evidence.
Base salary, overtime and bonuses
Base salary is the most reliable income in an assessment. Overtime, shift allowances and bonuses are often discounted or excluded unless they show a consistent history over a period of time. If a large share of your income is overtime, present that pattern clearly with payslips and a summary, rather than hoping the assessor will add it up for you.
Changing jobs and probation periods
Changing jobs during an application is one of the most common causes of late stage problems. Some lenders will not count income while you are in a probation period, and a new employer can reset the history they require. If a job change is on the cards, time it to happen after settlement. Talk to us before you resign, because the sequence matters more than the decision itself.
Deposit and Genuine Savings
Lenders want to see where your deposit came from, and saying you have been saving is not evidence on its own. Most assessments ask for statements that show savings building over time. A single large transfer from a relative or an unexplained source will trigger questions. When family money is involved, lenders typically ask for written confirmation that the funds do not have to be repaid.
Saving history over time
A steady pattern of deposits, even modest ones, reads far better than a lump sum that appears a week before contracts are exchanged. Keep the statements for the account where the deposit sits, and avoid moving money between accounts in ways that make the trail hard to follow. Clear records make the assessor’s job simple, and simple files move faster.
Costs beyond the deposit
The deposit is not the only cash a lender cares about. Stamp duty, valuation fees, conveyancing and lender fees all need funding. An assessor who sees the deposit fully consumed by these costs will question whether you have a reserve left for emergencies. Keep some savings after settlement, because a borrower with no cash buffer looks riskier even when the loan ratio sits within policy.
Pro tip: Keep the last three to six months of statements for your deposit account in one folder. Assessors ask for them early, and having them ready cuts down on the back and forth.
Property Valuation and Security
The property is the security for the loan, so the lender relies on a valuation to confirm it is worth what you are paying. If the valuation comes in below the contract price, the lender lends against the lower figure and the gap becomes your problem. Loan to value ratio, or LVR, is the measure they use. Deposits below 20 per cent usually bring lenders mortgage insurance into the picture, which adds to the cost of the loan.
Valuation gaps on Brisbane purchases
Valuations can lag behind a fast moving market or a recent sale that was pitched high. If you are buying in a suburb where comparable sales are thin, ask the agent for recent sales and expect the valuer to weigh them more heavily than the asking price. Build a small margin into your offer or your cash reserve for that scenario, because a shortfall found late is far harder to solve.
Investment property security and condition
Investment properties are assessed on comparable sales and rental evidence. Properties with significant defects, unusual construction or small or complex titles may be harder to lend against. Apartments can face tighter assessment depending on the building. Check the title, strata details and any visible defects early, because these details can change which lenders will accept the security.
Common Reasons Applications Get Declined
Most declines we see are preventable, and they cluster around a few patterns. The applicant has a clean income and decent savings, but the file contradicts itself. Documents do not match, a declared expense does not appear in the statements, or a new debt shows up during the process. Assessors read the whole file, and inconsistency erodes confidence faster than almost anything else.
Inconsistent declarations
When the income on your application differs from your payslips, or the employer on your tax return does not match your current role, the file goes back for clarification. Each round adds time, and a lender that loses patience may decline rather than keep chasing. Fill in the application with the same figures your documents show, down to the cent.
New debt during the application
Buying a car, opening a store card or financing furniture between pre-approval and settlement can change the serviceability result. Lenders often recheck credit before settlement. Hold off on new commitments until the loan has settled, even if the purchase feels small.
Gaps in documentation
Missing bank statements, unsigned forms or an incomplete tax return slow everything down. Missing items also send a signal about how the file will be managed. A complete file gets assessed faster, and that matters when the seller is waiting on a settlement date.
Assessment Rules for Specialised Scenarios
The core assessment is the same across most loans, but the weight lenders place on each factor shifts with the purpose of the loan. Refinance, investment and SMSF applications each raise different questions. Knowing which category your situation falls into lets you prepare the right evidence before the file is lodged.
Refinancing an existing loan
Refinance applications can move quickly because the security and repayment history are already on record. The lender still runs serviceability and will want current repayments and a clear picture of any cash being drawn out. If you are consolidating debts into the new loan, expect the consolidated amount to be assessed against your income, not just the old home loan balance.
Loan solutions for marital breakdown
Where a relationship has ended, lenders need to know who will be on the loan, who holds title and how any settlement payment is funded. A single income may now have to service the loan, and the assessor will test that position directly. Keep separation and property settlement documents together, because the file cannot move forward without them.
SMSF lending
SMSF loans are assessed with close attention to the fund itself, including its income, contributions, trust deed and the structure of the borrowing. Expect more documentation than a standard home loan requires. Get the fund paperwork ready early, because it is often the slowest part of the file.
| Loan Purpose | What Lenders Focus On | Common Cause of Delay |
|---|---|---|
| Refinance | Current repayments, the amount of cash drawn out and whether the new structure is more sustainable | Loan balance increases that have no clear explanation |
| Investment property | Rental evidence, discounted rental income and existing debts across every property held | Rental income not supported by a lease or appraisal |
| SMSF | Fund income, contributions, trust deed and the structure of the borrowing | Fund documents missing or out of date |
Preparing Your Application Before Lodgement
Preparation is where most of the value sits. Applications that move quickly are the ones where the borrower has already answered the questions an assessor will ask. A complete file with consistent figures is worth more than a slightly sharper rate attached to a messy file.
Build a document pack
Gather about three months of bank statements, recent payslips, two years of tax returns if you are self-employed or have variable income, and evidence of your assets and liabilities. Put everything in one folder with a checklist. Missing items are one of the most common reasons files stall, so check the list twice before lodging.
Use one point of contact
A single contact who knows your file avoids the frustrating situation where different people ask for the same documents. Mortgage World was founded in 2004 by Gary Willmott, and clients work with one point of contact through flexible meeting options and digital tools for sharing information. That continuity matters when an assessor comes back with a question three weeks after lodgement.
Get a pre-assessment before you commit
Before you make an offer or sign a contract, have your serviceability tested at the buffer rate and your credit file checked. We work with a range of trusted partner lenders, so the assessment can be matched to the lender whose policy fits your income structure, rather than forcing your file into a single product.
Pro tip: Ask for the assessment in writing, including the rate used and the living expense benchmark applied. If a figure looks wrong, you can correct the inputs before the file goes to credit rather than after a decline.
Frequently Asked Questions
What do lenders look at most when assessing a home loan?
Lenders focus on serviceability, which is whether your income can cover repayments after living costs and existing debts. They also review credit history, the deposit and its source, and the valuation of the property. Most declines trace back to one of these four areas.
What is the serviceability test for a home loan in Brisbane?
The serviceability test measures whether you can make repayments at a rate higher than the one offered. Under the regulator’s guidance, lenders apply a buffer of at least 3 percentage points. The same test applies to Brisbane borrowers whether they buy a family home or an investment property.
Can I get a home loan if I am self-employed?
Yes, but the assessment relies on documents rather than what you say about your business. Lenders typically want two years of tax returns and business financials, and they may use a different calculation to work out your income. Organised records make a real difference to how your file is read.
Does an unused credit card affect my borrowing power?
It can. Lenders generally assess credit card limits as if they were fully drawn, even when the balance is zero. Closing cards you do not use can improve your position, though you should check how the change affects your credit file before you act.
How long does a home loan assessment take?
The timeline depends on how complete your file is at lodgement and how quickly you respond to questions. A complete file with consistent figures avoids most of the delay. Incomplete files and job changes during the process are the most common causes of longer timeframes.
Do I need pre-approval before I make an offer on a property?
Pre-approval is not a guarantee of final approval, but it shows that your serviceability and credit have been assessed in principle. It also helps you set a realistic budget before you bid. Final approval still depends on the property valuation and any changes to your circumstances.
Which part of your home loan assessment surprised you most, and what would you tell another borrower about getting it right the first time?
References
- Experian explainer on the factors mortgage lenders consider when reviewing applications
- Freddie Mac overview of the four factors used to qualify for a mortgage
- Wells Fargo guide to the five Cs of credit that lenders assess
- Capital Bank tips for improving mortgage eligibility before applying