
Ask a room full of property investors how their lender treats rent and you will hear a dozen different answers, most of them wrong. Rental income can strengthen a home loan application in Brisbane, but it rarely counts the way the owner expects. A property that looks cash-flow positive on a spreadsheet may add far less to borrowing power once the assessor has finished the sums. This article explains how lenders calculate rental income when assessing an investment loan, which evidence they accept, and what you can do before you lodge a rental income home loan assessment Brisbane application.
Table of Contents
- Quick Takeaways
- How Lenders Read Rental Income on an Investment Loan
- Rental Income Shading and the Haircut Lenders Apply
- Serviceability Buffers and Why Rent Alone Rarely Carries a Loan
- Documenting Rental Income So the Assessor Can Verify It
- Comparing Rental Evidence Types Side by Side
- Tax Returns Versus Lender Assessment
- Untenanted and New Build Investments
- Frequently Asked Questions
- References
Quick Takeaways
| Key Insight | Explanation |
|---|---|
| Lenders count only part of your gross rent | The assessor discounts the rent before adding it to your income, so the full figure on the lease never flows straight through to borrowing power. |
| Rent supports the application, it does not replace income | Your own income still has to carry the loan under the serviceability test, with rent acting as a supporting figure rather than the foundation. |
| A current signed lease carries the most weight | A lease gives the assessor something specific to verify, including the rent, the term and the tenant details. |
| Short or informal tenancies weaken the figure | Lenders favour leases with a clear term. Month-to-month arrangements or verbal agreements are harder to rely on. |
| Your tax return and your lender look at different numbers | Deductible interest and depreciation reduce your taxable income, but that does not automatically increase the rent a lender will count. |
| Test the scenario before you sign a contract | Ask your broker to run the loan with the shaded rent figure before you commit to a purchase price, not after. |
How Lenders Read Rental Income on an Investment Loan
When an assessor reviews an investment loan, rent is one line in a wider serviceability calculation. The lender adds your assessable income, deducts living expenses and existing debts, and tests whether the repayments would remain affordable at a higher assessment rate. Rent from the new property enters that calculation as a discounted figure, never as the full amount written in the lease.
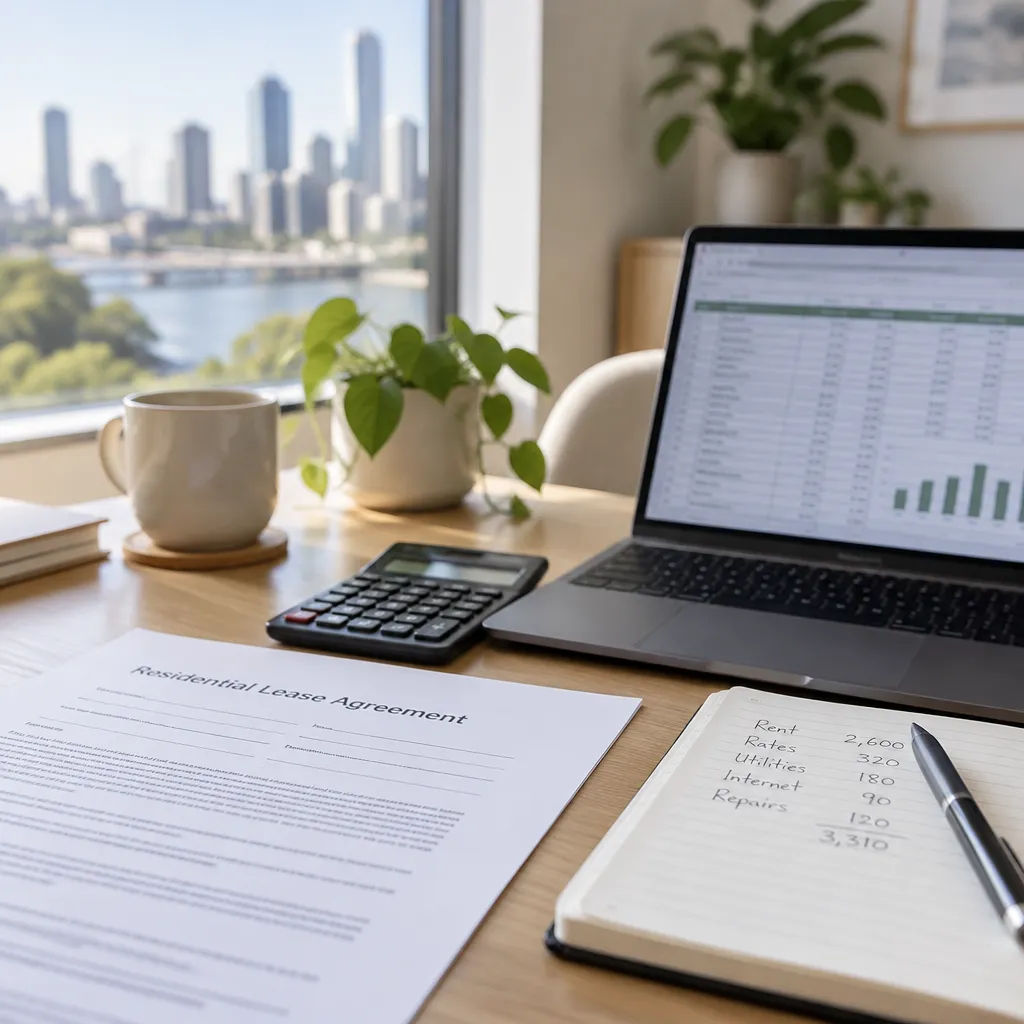
Gross rent versus assessed rent
Gross rent is the figure in the lease, usually expressed weekly, before anything is taken out. Assessed rent is the portion the lender chooses to count, and the gap between the two is where most investors get caught out. If you buy on the basis of the listing agent’s rent estimate, you are planning around a number the lender will never fully accept.
In practice, the first conversation with a broker should separate these two numbers clearly. Write down the gross rent, then work out what the assessor is likely to count, and build your deposit and cash buffer around the second figure.
Why lenders treat rent as unreliable
Lenders have seen plenty of vacancies, tenants who leave early, and landlords who overestimate what a property will rent for. A house can sit empty between tenancies, and rent can fall when the local market softens. The assessor prices that risk into the formula, which is why the discount exists in the first place.
Investors sometimes read this as the lender being unfair to property. It is better understood as a risk control. The lender is betting that the loan can be repaid even when the rent stops arriving, and the shading is how it builds that margin into the numbers.
Rental Income Shading and the Haircut Lenders Apply
Shading, sometimes called a haircut, is the discount an assessor applies to gross rent before it counts toward your income. Each lender sets its own policy, and those policies change over time. Any figure you read online should be checked against the current policy of the lender you are actually applying with.
The practical result is simple. The rent you see on a listing is rarely the rent that will help your application, so the purchase decision should work even if the shaded figure is much lower than expected.
How shading interacts with the new loan repayments
Shading does not reduce the new loan repayments. The lender still tests the full loan against your income, and it adds only a portion of the rent to offset that cost. This is why an investment that looks cash-flow neutral on paper can still fail an assessment when your existing commitments are heavy.
Many investors also forget about other debts, such as personal loans, car finance and credit cards. Those commitments reduce the margin before any rent is counted, so a clean debt position often matters more than the rent figure itself.
A common mistake with rent estimates
A common mistake is to treat a rent appraisal as settled income. An appraisal is an estimate, and the assessor will discount it further than a signed lease. If you need the purchase to work, build the budget on your own income first and treat any rent as a bonus that may or may not be counted in full.
Pro tip: Ask your broker for two versions of the serviceability calculation, one with rent counted and one without. If the loan only works when rent is counted at close to full value, the purchase price is probably too high for your current position.
Serviceability Buffers and Why Rent Alone Rarely Carries a Loan
Lenders do not test your ability to repay at the rate you are actually paying. They test it at a higher assessment rate, often called a buffer, which gives them room if interest rates rise. The buffer applies to the whole loan, and the rent offset is then added on top of your income after its discount.
For Brisbane investors, this combination matters most when they are buying a second or third property. Each new loan adds a repayment that must be tested in full, while the rent from each property is only partly counted. The more properties you hold, the harder it becomes to rely on rent as the difference-maker.
The assessment rate buffer
The assessment rate is usually set above the rate you will actually pay. Because the loan is tested at this higher rate, the repayments in the calculation look larger than your real repayments. That is intentional, and it protects both you and the lender if rates move.
The effect is that a loan which feels comfortable at today’s rate may fail the assessment. An experienced broker will check the buffer before you fall in love with a property, not after you have made an offer.
Existing debts and the household budget test
Lenders also estimate living expenses, sometimes using a benchmark rather than your actual spending. If your declared expenses are lower than the benchmark, the assessor will normally use the higher figure. Rent is then added to the picture, but only after those costs have been accounted for.
A working family with two children and a car loan can easily find that the rent from a new investment does not change the outcome. Clearing or reducing smaller debts before lodging an application is often more effective than negotiating over the rent figure.
Documenting Rental Income So the Assessor Can Verify It
Verified rent is worth far more than estimated rent. An assessor who can see a lease, a rent ledger or a bank record has something concrete to rely on, and that usually means a higher figure is counted. Documentation is where many applications are won or lost, and it is one of the easiest areas to tidy up before you apply.
Signed leases and their terms
A signed residential tenancy agreement shows the rent, the tenant, the start date and the term. Lenders prefer leases with a clear and reasonable term, because a longer commitment is more stable than an arrangement that can end at short notice. If your current tenancy is month-to-month, expect the assessor to be more cautious.
Make sure the lease matches the property you are financing. An assessor who finds a mismatch between the address, the rent or the parties will set the document aside, and the application can stall while you sort it out.
Rental appraisals for properties not yet tenanted
When a property is vacant or newly built, you will usually need a rental appraisal from a real estate agent. The appraisal estimates what the property should rent for, based on comparable properties nearby. It is useful, but it is an estimate, and most assessors give it less weight than a signed lease.
A common mistake is to ask for an appraisal that is optimistic. A figure that looks inflated will hurt your credibility with the assessor. A realistic appraisal, supported by comparable rents, is far more persuasive.
Bank statements and rent ledgers for existing investments
If you already own rental property, your bank statements and property manager’s rent ledger show whether rent is actually arriving. A consistent record over many months is persuasive evidence. Gaps in the record, or large arrears, tend to reduce the figure the assessor will accept.
US guidelines are more prescriptive about rental history. Fannie Mae’s rules, which a lending information site summarises as a 75% rule, show how a formula-based approach can work when documentation is strong. Australian lenders apply their own policies, so the logic is similar but the numbers are not the same.
Comparing Rental Evidence Types Side by Side
Not all rental evidence carries the same weight. The table below compares the three most common types you will be asked to provide, and where each one tends to help. The right choice depends on whether the property is already tenanted and how much rent history you have.
| Evidence type | How the assessor usually uses it | Where it works best |
|---|---|---|
| Signed residential tenancy agreement | Forms the main basis for counted rent, after shading, and is checked against the term and the rent amount. | Properties with a current tenant on a clear fixed term. |
| Rental appraisal from an agent | Provides an estimate of market rent, which is often discounted further or given limited weight. | Vacant properties, new builds and purchases before a tenant is in place. |
| Bank statements and rent ledger | Shows that rent is actually received over time, which supports a track record for existing investments. | Established investors refinancing or buying again with a documented rental history. |
In my view, a signed lease on a fixed term is the strongest evidence you can bring. An appraisal is useful for planning, but it should not be the only figure in the application. Bank records are the best tool for proving history, and they work well alongside a current lease.
The trade-off is timing. A new purchase rarely has a lease or a history, so the appraisal is the only option. That is why the purchase budget should work with the shaded appraisal figure rather than the optimistic one.
Tax Returns Versus Lender Assessment
Many investors assume that deductions on their tax return will help them borrow more. The tax return and the lender assessment look at different things, and the difference catches people out. The Australian Taxation Office allows you to claim interest on a loan used to buy a rental property, but that deduction reduces your taxable income rather than adding to your assessable income for borrowing purposes.
The ATO’s guidance also shows that the claim depends on how the loan is used. Interest is generally claimable on the portion of the loan used for a rental property, and only for the period the property is rented or held to produce rental income. Additional repayments that reduce the principal are not deductible, so the tax treatment is more nuanced than most investors expect.
What the ATO allows you to claim
The ATO example of joint borrowers shows how the claim is split. Two people take out a $350,000 investment loan to buy an apartment they hold as joint tenants, and they incur $30,000 of interest for a year when the property is rented out for the whole period. Each can claim $15,000 in their own return, which illustrates why the deduction follows ownership and use rather than the loan balance alone.
Interest is not the only expense. Repairs, certain renovations and depreciating assets can also be claimable, but each has its own rules. A tax adviser should confirm what applies to your situation.
Why deductions do not automatically add to borrowing power
A tax loss from negative gearing lowers your taxable income, but many lenders look at your income differently for serviceability. Some lenders add back certain non-cash deductions such as depreciation, while others do not, and policies vary. The safe assumption is that a tax benefit does not translate into extra borrowing capacity unless your lender confirms it in writing.
This is a common frustration for investors who have been advised by an accountant to hold property for tax reasons. The accountant is looking at your return, the broker is looking at the lender’s policy, and the two conversations need to happen together before you buy.
Untenanted and New Build Investments
Rental assessment gets harder when the property has no tenant yet. Off-the-plan apartments, new house and land packages and recently completed builds usually come with an appraisal rather than a lease. For investors buying in Greater Brisbane new estates, this is often the situation they face, and it changes both the lender’s view and the timing of the application.
House and land packages and the appraisal gap
With a house and land package, the lender may need to assess the completed value and the expected rent before a tenant is in place. Rent evidence will usually be an appraisal, and the shaded figure may be lower than the investor hoped. Mortgage World’s House and Land Finance service is built for this stage, so the structure can be checked before a contract is signed.
Working with a builder can also add timing pressure. If your settlement and your tenancy do not line up, you may carry the loan repayments for several weeks with no rent coming in. That gap should be included in your cash buffer from the start.
Using a builder broker arrangement to plan the numbers
When you are buying through a builder, the finance conversation should happen before the design and inclusions are locked in. Builder Broker support helps match the loan structure to the build timeline, the appraisal, and the expected income. That is far easier than discovering a shortfall after the contract is signed.
For investors buying a second property, the Investment Property loans service looks at the full portfolio, including existing repayments and rental history. A clear plan for the new property, with a realistic appraisal and a sensible cash buffer, is the strongest position to take into an assessment.
Pro tip: Ask the lender how it will treat the rent before the property is tenanted, and get the answer in writing. A verbal assurance from a sales consultant does not change the assessment, and it can leave you exposed if the policy is different at the time you apply.
Frequently Asked Questions
Do lenders count the full rent from my investment property?
No. Lenders apply a discount to gross rent before they add it to your assessable income. The exact discount depends on the lender and its current policy, so the figure you are shown on a listing is rarely the figure that will help your application.
Can I use rent to qualify for a loan if I am not yet tenanted?
Sometimes, but the evidence is usually a rental appraisal rather than a signed lease. Most assessors give an appraisal less weight, so the purchase should be planned to work even if little or no rent is counted.
Does negative gearing increase how much I can borrow?
Not automatically. The tax loss reduces your taxable income, but lenders assess serviceability on their own terms. Some add back certain non-cash deductions, while others do not, so ask your broker how your lender treats them.
What rental documents should I prepare before applying?
Gather a signed tenancy agreement for each rental property, a current rent ledger or bank statements showing rent received, and any rental appraisal for vacant properties. Make sure the addresses and rent amounts match across all documents.
Why does a higher assessment rate affect my rental income calculation?
The assessment rate is a buffer used to test whether the loan remains affordable if interest rates rise. It makes the repayments in the calculation larger than your actual repayments, which means the loan has to fit a more demanding test before rent is added.
Have you had a lender count your rent differently from what you expected, or found a documentation step that made a real difference to your application? Share your experience in the comments so other Brisbane investors can learn from it.