
Can you have the certainty of a fixed rate and the freedom of a variable one on the same home loan? For many Brisbane borrowers the answer is yes, through a structure that divides one mortgage into two portions, usually one fixed and one variable. The setup is simple, but it is often done badly, either as a 50:50 default or with features that don’t match how the household actually spends and saves. This guide explains how a split works, where the trade-offs sit, and how to decide whether it suits your cash flow and plans.
Table of Contents
- Quick Takeaways
- Split Home Loan Brisbane: How the Structure Works
- The Fixed Portion: What You Gain and What You Give Up
- The Variable Portion: Offset, Redraw and Extra Repayments
- Choosing Your Split Ratio
- Using Different Fixed Terms Across Splits
- Split Versus Single-Rate Loans
- Common Mistakes With Split Home Loans
- Who a Split Home Loan Suits in Brisbane
- Frequently Asked Questions
- References
Quick Takeaways
| Key Insight | Explanation |
|---|---|
| Split ratio is a risk decision | A 60:40 split on a $500,000 loan puts $300,000 on fixed and $200,000 on variable. Pick the ratio your budget can carry if rates rise, not the one that looks balanced. |
| The fixed portion buys predictability | Repayments on that slice stay the same for the fixed term and are protected from rate rises, but they won’t fall if rates drop. |
| The variable portion carries the flexibility | Offset and redraw sit on the variable side, and extra repayments are often allowed there, subject to the product terms. |
| Use different fixed terms on different splits | Some products offer one, two or three year fixed terms, so your rate reviews don’t all land in the same year. |
| You can split at any time | Splitting at settlement is common, but you can also split later, or refinance into a split as your circumstances change. |
| Check break costs and extra repayment rules first | Ask for break costs in writing and confirm whether extra repayments are allowed on the fixed portion before you sign. |
Split Home Loan Brisbane: How the Structure Works
A split home loan divides one mortgage into two or more portions, each with its own interest rate and features. In most cases you have one portion fixed and one variable, although some borrowers split into more than two. The lender calculates interest and repayments on each portion separately, which is why the setup has to be checked line by line, not just at the headline rate.
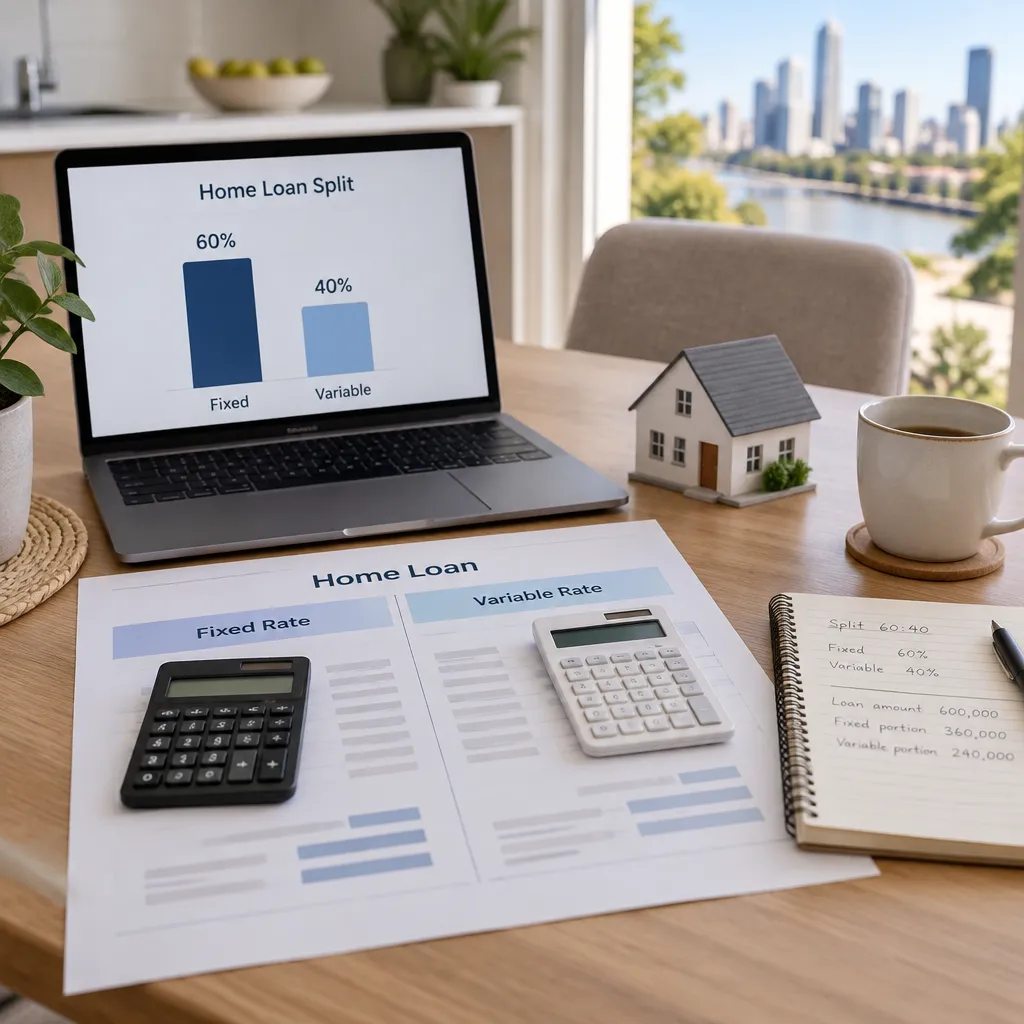
The proportion is the first decision you make. A worked example often used in lender guides is a $500,000 loan split 60:40, which puts $300,000 on a fixed rate and $200,000 on a variable rate. The fixed slice gives predictable repayments on $300,000, while the variable slice moves with the market and carries the flexible features.
How the Portions Are Divided
Splits are not limited to 60:40. A 70:30 or 50:50 mix is just as workable, and the right choice depends on how much of your budget you want locked down. The number matters less than the reason behind it, so decide what the fixed portion must cover before you pick a percentage.
Think about the repayment you need to be certain of. That figure is the floor for the fixed side, and everything above it can sit on variable where you have more room to move.
When You Can Set Up a Split
You can split at settlement or at any point during the loan, as your circumstances change. That matters for Brisbane households whose needs shift, whether through a change in income, a new expense or a planned renovation. If you already have a single loan, a refinance is often the natural moment to build the split, and our Refinance Loans service can set the structure up in the same process.
The Fixed Portion: What You Gain and What You Give Up
The fixed portion is the certainty slice. Repayments on that amount stay the same for the fixed term, which makes monthly budgeting far easier if your income is steady but your costs are not. It also protects that portion if rates rise during the term.
A fixed rate buys predictability, not a better price. Its value shows up when rates rise, and its cost shows up when they fall.
The trade-off is clear. If rates fall, the fixed portion does not benefit, so you keep paying the locked rate while variable borrowers see their repayments drop. Choose the fixed term with that in mind, not only the rate on the day you sign.
What the Fixed Slice Protects You From
Rate protection works like insurance on a specific amount. On a $300,000 fixed portion, a rise in rates does not touch repayments until the term ends. That is the feature most worth paying for when your budget has little room for a surprise increase.
The Cost of Leaving a Fixed Loan Early
Breaking a fixed rate early can attract break costs, and those costs can be significant when rates have moved. Some fixed loans also limit extra repayments, so check whether you can pay down the fixed slice faster before you assume you can. Products vary, which is why the fine print matters as much as the headline rate.
Pro tip: Ask for the break cost calculation in writing before you lock the fixed portion, and ask how extra repayments on that portion are treated.
The Variable Portion: Offset, Redraw and Extra Repayments
The variable portion is where a split earns its flexibility. It moves with the market, so repayments can rise or fall, but it typically carries the features that make a split worth having, such as redraw and an offset account. Those features are the reason many borrowers accept some rate uncertainty on this side.
How an Offset Account Works on a Split
An offset account linked to the variable portion reduces the balance that interest is charged on. Money in the offset lowers that balance, so you only pay interest on the difference. Savings sitting in an ordinary transaction account earn little, so moving them into the offset is often the simplest gain available on the variable side.
Redraw and Extra Repayments
Many variable products allow extra repayments, and redraw lets you reach those extra funds later if you need them. Both depend on the product, so confirm the rules before you rely on them. Extra repayments shorten the loan, while redraw gives you a way back to the money without reapplying.
If rates fall, your repayments do not change automatically. You can choose to lower them, or keep paying the old amount to clear the loan sooner, and that second option is the one most borrowers overlook.
Pro tip: When rates drop and your repayments stay the same, keep paying the old amount. The difference goes straight to reducing the balance and shortens the loan.
Choosing Your Split Ratio
The split ratio is a risk decision, not a guess. A heavier fixed portion gives you more certainty and less flexibility. A heavier variable portion gives you more room for extra repayments and offset savings, but leaves more of your budget exposed to rate moves.
Avoid a 50:50 split just because it looks balanced. Start from your cash flow instead: what repayment would you still be comfortable making if rates rose, and the fixed term ended at a higher rate? The portion you can carry under a tougher scenario is the portion you should fix.
Pro tip: Stress test the variable portion at a rate above the one you are offered. If the household budget still works, the split is realistic. If it doesn’t, fix more.
Heavier Fixed or Heavier Variable: Who Each Suits
A heavier fixed split suits borrowers on a tight budget who need repayments they can predict, such as first home buyers with a thin cash buffer. A heavier variable split suits people who expect to make regular extra repayments, are building an offset balance, or expect their income to rise over the loan term.
Stress Testing the Variable Slice
Build the scenario with your real figures: current repayments on the variable portion, a higher rate, and the monthly amount you can put into the offset. If the numbers still work when the variable rate rises, the split can handle an ordinary cycle. That check is more useful than comparing headline rates across providers.
Using Different Fixed Terms Across Splits
One of the most useful features of a split is that each portion can have a different fixed term. Some products offer one, two or three year fixed terms, so you can choose a term for each split rather than accepting one term across the whole loan. The practical effect is that your rate reviews don’t all arrive in the same year.
Staggering Your Expiry Dates
Suppose one slice is fixed for one year and another for three years. When the one-year fix ends, you re-fix only part of the loan, while the rest keeps its rate. You never face a single moment where the whole loan reprices at once.
Staggering works best when the expiry dates fall in different budget years. Be careful that a short fixed term does not push you into a reset at a bad point in your finances, such as during a planned renovation.
Topping Up a Split for Renovations
A top up can sit on its own split with its own term. Some borrowers top up to fund a renovation or a vehicle, then repay that amount over a different term while the main loan still clears within its original timeline. That keeps the shorter-term repayment separate from the long-term home loan.
Make sure the lender treats the top up as a new split, not a change to the existing term. At the end of each fixed term you can re-fix or move that portion to variable, so you are never locked into split rates for the life of the loan.
Split Versus Single-Rate Loans
A split is rarely the right answer for everyone. Before you set one up, compare it with the two single-rate options so you can see what you are giving up. The table below sets out the main differences in practical terms.
| Loan structure | Best for | Main trade-off |
|---|---|---|
| Single fixed loan | Borrowers who want fixed repayments across the whole loan | Little benefit if rates fall, and break costs if you exit early |
| Single variable loan | Borrowers who plan regular extra repayments and want full offset and redraw access | Repayments rise with the market and can be harder to budget |
| Split home loan | Borrowers who want certainty on part of the loan and flexibility on the rest | More setup decisions, and each portion has its own rules to monitor |
The split is a middle path, not a shortcut. It takes more attention because each portion has its own rules, so it pays off most for households that review their loan at least once a year. If you want one simple repayment and nothing else to track, a single loan may be the better fit.
Common Mistakes With Split Home Loans
The most common mistake is choosing the split by default rather than by design. Borrowers pick 50:50 because it feels balanced, then discover that the fixed portion limits extra repayments or that the offset is not attached to the account they actually use.
Setting Up the Split Without Checking Features
Confirm the features on each portion before you sign: offset, redraw, extra repayment rules and any limits on the fixed side. A split that sounds flexible on paper can be restrictive once you try to use it. Ask for the rules in writing, not just a verbal summary.
Forgetting the Re-Fix Date
Many borrowers only look at their loan again when the fixed term ends, by which time rates have moved and the choice is effectively made for them. Put each expiry date in your diary and review the options well before it arrives. Ask what it would cost to exit or re-fix, and when the next decision point falls.
Who a Split Home Loan Suits in Brisbane
Working families in Greater Brisbane often need predictable repayments, but they also want to make extra payments when a bonus or a tax refund arrives. A split lets you do both without forcing one choice across the entire debt. That balance is the main reason it appeals to busy households.
First home buyers often use a split while they learn their budget, then move more of the loan to variable once their cash flow is clear. Our First Home Loans service covers low rates and flexible terms, and we can show how a split would sit alongside that. Investors often keep investment debt separate from owner-occupied debt, because how the funds are used affects tax deductibility. Speak with your accountant before you set that up.
A split can also be part of a broader plan for building. If you are using House and Land Finance or Builder Broker, plan the split around your construction timeline and progress payments, not just the final loan amount.
Mortgage World was founded by Gary Willmott in 2004 and brings over 25 years of experience to home loan clients. Our team holds a Certificate 4 in Finance brokering, we have been FBAA members for 20 years, and we operate as a licensed credit representative under Finsure Finance & Insurance (ACL 384704). Our office at Lvl 1, 1 Miles Platting Rd, Eight Mile Plains, QLD 4113 is by appointment only. Call 1300 932 663 or email info@mworld.com.au to talk through your options.
Frequently Asked Questions
Can I split my home loan after I have already settled?
Yes. You can split at settlement or later, as your circumstances change. If your current loan is a single product, a refinance is often the cleanest route to a split structure.
What is a common split ratio for Brisbane borrowers?
There is no standard ratio. A 60:40 split is a worked example used in many lender guides, but the right ratio is the one your budget can carry if rates rise when the fixed term ends.
Can I make extra repayments on the fixed portion?
Some fixed products allow additional repayments and others limit them, so check the product terms before you assume it. Extra payments on the variable side are usually more flexible, which is why many borrowers direct spare cash there.
What happens when the fixed term ends?
You can re-fix that portion, move it to a variable rate, or choose a different term. You do not have to stay split for the life of the loan, but you should review the options well before the expiry date.
Is a split home loan a good option for first home buyers?
It can be, particularly if you want repayment certainty while learning your budget and still want offset or redraw access. We can compare a split against a single loan for your situation, so you can see the numbers side by side.
Have you split a home loan yourself, and what made you choose your fixed to variable ratio?
References
- Explainer on how a split home loan divides fixed and variable portions, with a worked example
- Pros and cons of split home loans, including choosing different fixed terms
- Comparison of fixed and variable rate trade-offs for home borrowers