
Greater Brisbane buyers often ask the same question first: which First Home buyer grants can we actually claim, and does the grant change how much we can borrow? The honest answer is that Queensland’s main payment, the First Home owner grant, is narrower than most people expect. It pays $30,000 on eligible new homes valued under $750,000, and it pays nothing on an established house, however first-time you are. This guide sets out what the grant covers, where buyers get caught out, and how it sits alongside stamp duty concessions and other state schemes.
Table of Contents
- Quick Takeaways
- How Much the First Home Owner Grant Pays
- Who Qualifies for the Grant in Greater Brisbane
- Owner-Builders and Builder Contracts
- How the Grant Sits Alongside Stamp Duty Concessions
- State Schemes Beyond the Grant
- Comparing New, Established and Owner-Built Routes
- Building Your Application Around the Grant
- Frequently Asked Questions
- References
Quick Takeaways
| Key Insight | Explanation |
|---|---|
| Grant amount depends on contract date | Eligible new home contracts signed on or after 20 November 2023 receive $30,000. Contracts signed before that date receive $15,000. |
| The $750,000 cap includes land | The home and land value must be less than $750,000, including any contract variations. At $750,000 or more, the grant is lost entirely. |
| No grant for established homes | First-time buyers of established homes are not eligible for the grant, but may still qualify for a transfer duty concession. |
| The $30,000 rate continues for new contracts | The Queensland Government guidance says the increased $30,000 grant continues for eligible contracts signed from 1 July 2026 going forward. |
| Every co-applicant is assessed | Spouses, de facto partners of two years or more and registered partners must all meet the criteria, so check each applicant’s position. |
| Owner-builders are timed by foundations | The $30,000 rate applies where foundations were laid on or after 20 November 2023. Your land purchase date does not set the rate. |
How Much the First Home Owner Grant Pays
The First Home owner grant is the core First Home buyer grant in Queensland, and it is the figure most Greater Brisbane buyers see quoted first. Depending on your contract date, you may qualify for $15,000 or $30,000 toward buying or building a new home. The grant is a payment toward the purchase, not a tax refund, and it is a separate program from stamp duty concessions.
The rate depends on the date your contract was signed. For eligible contracts signed on or after 20 November 2023, the grant is $30,000. For contracts signed before that date, it is $15,000. Owner-builders are measured differently, which we cover later in this guide.
Why the Contract Date Drives the Amount
Many buyers assume the grant follows the settlement date or the date they moved in. It does not. The contract signing date is what locks in the rate, so a house that settles in early next year can still fall under the rate that applied when the contract was signed.
A common mistake is to plan a budget around the rate you saw in an advertisement or a builder’s brochure. Those materials can be out of date, so the rate should be checked against the official guidance before you commit.
Checking the Current Rate Before You Sign
The Queensland Government has said the boosted grant continues beyond 30 June 2026. Its guidance also states that the increased $30,000 grant will continue for eligible contracts signed from 1 July 2026 going forward. For a contract signed in late 2026, the current rate applies, not the rate that existed when you first started looking at properties.
State settings can change, so treat any grant figure as a starting point until you have confirmed it against the official pages. Keep a dated screenshot or saved copy of the guidance you relied on, and note the date you checked it.
Who Qualifies for the Grant in Greater Brisbane
Eligibility is assessed on the transaction and on the applicants. You need an eligible new home contract, and every applicant in the household must meet the criteria. Most rejected claims fail on one of three points: the value cap, the new home test, or the status of a co-applicant.
The $750,000 Value Cap
The value of your new home must be less than $750,000, including land and any contract variations. If the value is $750,000 or more, you are not eligible. The cap is applied to the total of the home and land, not the build price alone.
Variations are where this cap most often catches people. A builder’s upgrade, a driveway, or a changed inclusion can push a contract over the line after signing. Get every variation in writing and add it to the total before you accept it, not when settlement is close.
New Homes Only, and What Counts as New
The grant only applies to new homes. A new home is one that has not previously been occupied or sold as a place of residence, or a substantially renovated home. Since 1 December 2020, a home acquired under a builders’ terms arrangement may also count as new.
If the house has been lived in, even briefly, the grant is unlikely to apply. Ask the seller or builder directly whether the property has previously been occupied, and get the answer in writing before you pay a deposit.
Couples, Spouses and Co-Applicants
Before you and any co-applicants apply, you and your spouse must each have an eligible transaction and meet the other criteria. This covers married couples, de facto partners who have lived together on a genuine domestic basis for two years or more, and registered partners under the Civil Partnerships Act 2011.
In practice, a couple where one partner has property history elsewhere cannot treat the application as a simple single-name claim. Review each applicant’s history, not just the person leading the loan application.
Owner-Builders and Builder Contracts
Most Greater Brisbane buyers purchasing a new home will be doing a house and land package or an off-the-plan contract. These are normally documented in a builder’s contract, and the grant rate depends on when that contract was signed. Owner-builders follow a different timing test, so the two routes need to be handled separately.
House and Land Packages
A house and land package is a single contract covering both the home and the land, often through a builder working with an established land developer. The grant applies to the total value, including land. This is where the $750,000 cap catches people, because the land price, build price and variations all count toward the total.
In practice, the advertised package price often leaves out site works, connections and selected inclusions. Ask for a full written breakdown that shows land, build, site costs and variations before you sign, and check the total against the cap.
Owner-Builders and the Foundations Test
If you are building your own home as an owner-builder, the timing test is different. The $30,000 rate applies where foundations were laid on or after 20 November 2023. Where foundations were laid before that date, the grant is $15,000.
This matters for anyone who started a build a while ago and is now finishing it. Check the date the foundations were laid, not the date you bought the land or drew up the plans. Those dates are often months apart, and the difference can change the grant amount.
The grant is only as good as the contract behind it. Check the date, the price and the property’s history before you sign, not after exchange.
How the Grant Sits Alongside Stamp Duty Concessions
The grant is separate from the first home transfer duty concessions, and most buyers mix the two up. The grant is a payment toward the purchase. Transfer duty, commonly called stamp duty, is a tax on buying property in Queensland, and concessions can reduce or remove it for eligible first home buyers.
The split is straightforward. If you are buying an established home as a first-time buyer, you are not eligible for the grant, but you may qualify for a first home concession on transfer duty. If you are buying or building a new home, you may be entitled to a full transfer duty concession in addition to the grant.
Established Homes: Concession Without the Grant
Established homes are common across Greater Brisbane, particularly in older suburbs, and first-time buyers often assume the state will pay them something on top of the price. It will not, at least not through the grant. For an established home, the transfer duty concession is the question to answer.
Check the transfer duty rules directly with the Queensland Revenue Office before you make an offer, because concession rules are separate from grant rules. A cheaper established home can still come out ahead once concessions are included, so compare the total cost of both routes.
New Homes: Combining the Two Benefits
On a new home, the two benefits can work together. A buyer who qualifies may receive both the grant and a full transfer duty concession. Whether a concession applies to your specific price and property should be confirmed before exchange, because the value of the home determines the outcome.
Pro tip: Ask your broker or conveyancer to model your transfer duty and grant together before you sign. Buyers who only check one of them often discover the gap after exchange, when changing the contract is no longer simple.
State Schemes Beyond the Grant
The First Home owner grant is not the only state support available to buyers in Queensland. Several programs run alongside it, and each has its own conditions, lender requirements and dates. Mixing them up is a quick way to lose money you were counting on.
Boost to Buy and the Approved Lender Rule
Boost to Buy is one of the Queensland programs buyers ask about alongside the grant. The Queensland Treasury information states that to apply for Boost to Buy, you must use the approved lender for your home loan, which it names as Unity Bank.
That is a hard requirement, not a preference. If your existing lender is not the approved lender, the scheme may not be open to you, however well you meet the other criteria. Raise the lender question at the start, before you choose a loan product, because switching lenders late can cost you time.
Stamp Duty Relief on New Builds
Queensland’s government initiatives pages also list a program described as no stamp duty for first home buyers on new builds. Treat that as a headline to verify, not a guarantee. The conditions, price limits and dates on state programs change, so the official page should be your reference point.
Our practical approach is to list each scheme, its eligibility conditions and its official source, then check that list against your contract date. That gives you one document to review before you sign, rather than a set of half-remembered rules from different websites.
Comparing New, Established and Owner-Built Routes
The three main routes into a first home in Greater Brisbane produce very different grant outcomes. The table below sets out the position for each, along with the point most likely to change your result.
| Route | Grant Position | What to Watch |
|---|---|---|
| New home (house and land or off-the-plan) | $30,000 for eligible contracts signed on or after 20 November 2023, with the home and land valued under $750,000 | Variations and site costs can push the total over the cap after signing |
| Established home | No first home owner grant | A transfer duty concession may apply, so check the rules with the Queensland Revenue Office |
| Owner-built home | $30,000 where foundations were laid on or after 20 November 2023, or $15,000 where they were laid before | The foundations date sets the rate, not the land purchase date |
Choosing the Route That Fits Your Budget
If your budget is tight, a new home under the cap may deliver more total support than an established home, but only if the build price, land and variations stay within $750,000. Run the numbers for both routes before you decide. Include the grant, any transfer duty concession, and the variations you are likely to add.
The wrong comparison is the advertised price against the advertised price. The right comparison is the all-in cost after concessions, with a realistic allowance for site works and changes. That is usually where the decision becomes clear.
Building Your Application Around the Grant
The grant is only one part of the purchase, and it has to fit into your home loan and your contract timetable. Our role as a broker is to line up the grant rules, the lender requirements and the builder’s timeline so none of them surprise you late in the process. This matters most for buyers using a house and land package, a builder broker arrangement or a first home loan with a building component.
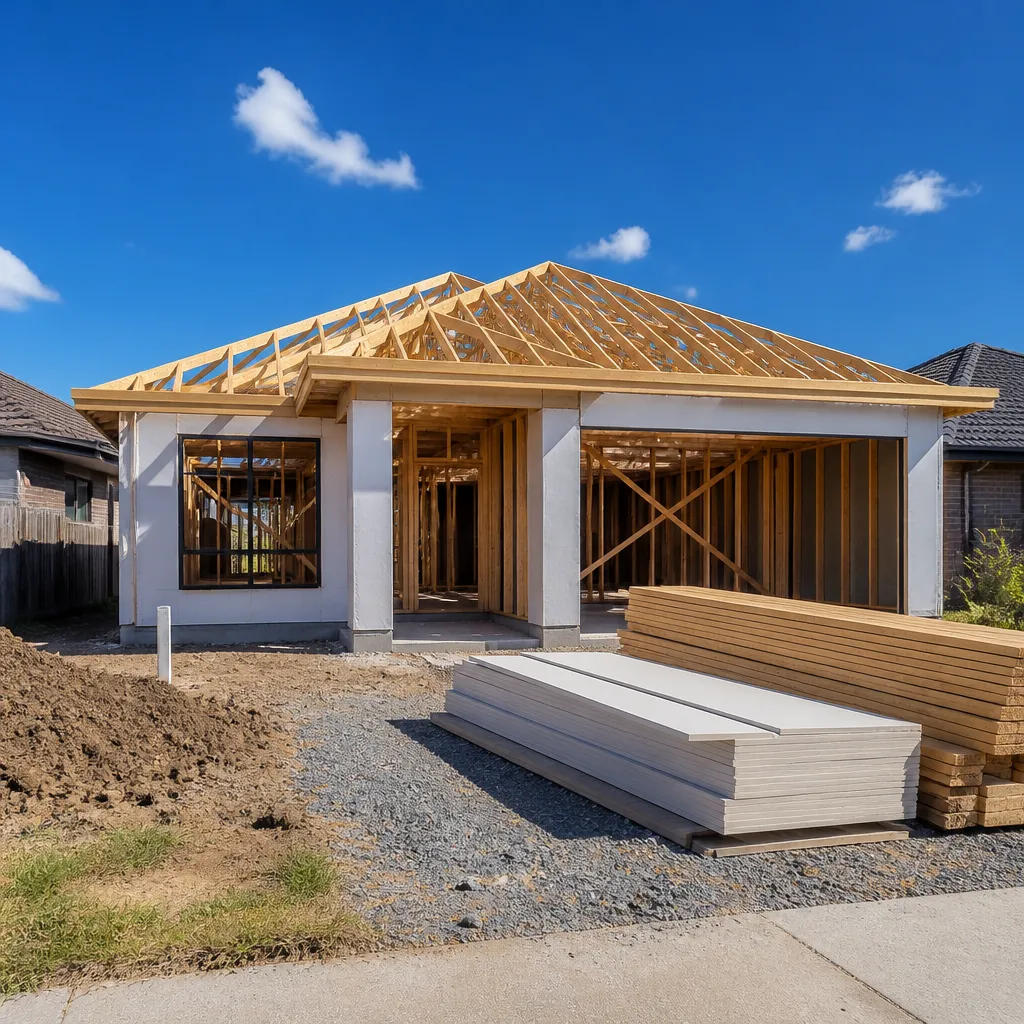
Timing the Contract, Deposit and Loan Approval
Your contract date sets the grant rate, and your loan approval needs to match the final price, including variations. If the approval is based on an earlier figure, a late variation can create a shortfall right before settlement. Ask your lender how they handle variations and whether they need a fresh valuation.
Pro tip: Before you exchange on a house and land contract, ask the builder for a single written figure covering land, build, site costs and all variations. Compare that figure against the $750,000 limit and against your loan amount in the same conversation.
Documents That Slow Applications Down
Gather your signed contract, the builder’s price breakdown, the variation schedule, identity documents and evidence of any spouse or partner status early. Missing paperwork often causes delays, and delays can put a settlement date at risk. A complete file on day one is worth more than a fast first submission with gaps.
Mortgage World works with a range of trusted partner lenders, and we keep one point of contact for each client so the grant, the loan and the contract are reviewed together. Flexible meeting options and digital document sharing help when the builder timeline moves faster than expected.
Frequently Asked Questions
Can I claim the First Home owner grant on an established home in Queensland?
No. The grant applies only to new homes, which include homes not previously occupied or sold as a place of residence, and substantially renovated homes. You may still qualify for a first home concession on transfer duty when buying an established home.
How much is the First Home owner grant in Queensland?
For eligible new home contracts signed on or after 20 November 2023, the grant is $30,000. For contracts signed before that date, it is $15,000. Owner-builders are assessed by the date their foundations were laid rather than the contract date.
Does the $750,000 cap include the land?
Yes. The value of the new home must be less than $750,000, including land and any contract variations. If the total reaches $750,000 or more, the grant is not available.
Can both partners in a couple apply for the grant?
Each applicant must meet the eligibility criteria. Spouses, de facto partners who have lived together on a genuine domestic basis for two years or more, and registered partners are all assessed, so you should check the position of every applicant before lodging.
Is the $30,000 grant still available for new contracts?
The Queensland Government guidance says the increased $30,000 grant continues for eligible contracts signed from 1 July 2026 going forward. Because state settings can change, confirm the current rate on the official pages before you sign.
Do I have to use a specific lender for Boost to Buy?
Yes. The Queensland Treasury information states that you must use the approved lender for your home loan to apply for Boost to Buy, which it names as Unity Bank. Check the current conditions before you choose your loan product.
If you have recently worked through a Queensland grant claim on a new home or an established property, we would value hearing what helped and what caught you out.
References
- Official Queensland eligibility criteria for the first home owner grant
- Queensland Government guide explaining the grant and how it differs from transfer duty concessions
- Queensland Government update on extending the $30,000 first home owner grant
- Queensland Treasury information on Boost to Buy and its approved lender requirement